

PayPal - Pay, Send, Save
4.2

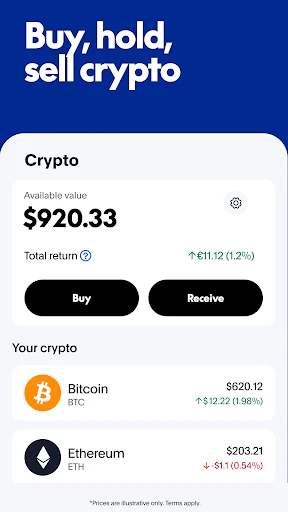
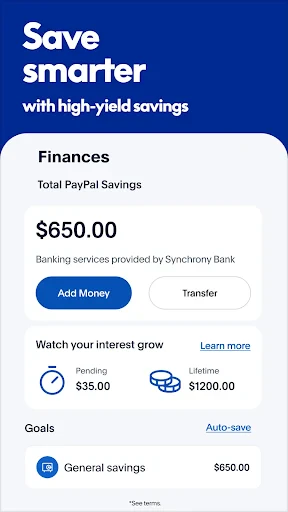
I judge a money app less by how quickly it can move a payment and more by whether I can stay deliberate when money is involved. A familiar name can make a service feel reassuring, but I still want to understand what I’m about to do, which account I’m using, and what choices are in front of me. That’s the lens I bring to PayPal - Pay, Send, Save: useful for everyday payments, but best treated as a financial tool that deserves a quick check before each tap.
Trust starts with the task, not the logo
PayPal Mobile’s finance app has a 4.2 average from around 3.6 million ratings, with roughly 432,000 written reviews and over 100 million installs. Those figures show that it is widely used, not that every transaction will suit every person. I see its strongest case in familiar, practical situations: paying an online merchant, sending money to someone whose PayPal details I know, or receiving a payment without having to coordinate cash.
The key distinction is that a payment app is a route for handling money, not a substitute for paying attention. Before confirming a transfer, I would check the recipient and amount, then pause over the funding method and any displayed terms. That small habit matters especially when a contact has a common name, a phone number has changed, or I am paying in a hurry. A convenient screen should make a task easier, not make the decision automatic.
Controls are useful only when I use them
Setting up means signing in or creating an account and connecting a bank account or card. I would take the time to review the available account and payment choices during that process instead of linking every possible source just for convenience. Keeping the setup focused can make it easier to recognize what I am using later. If I no longer want a particular payment source connected, I would look through the account controls rather than assume that deleting the app changes the account arrangement.
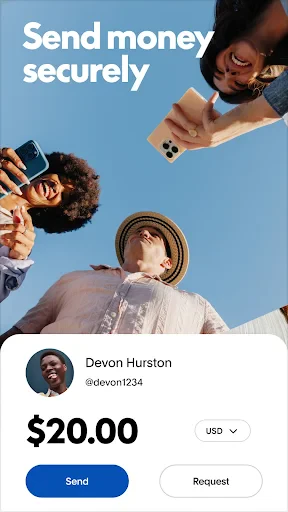
When sending money, entering an email address or phone number is quick, but speed creates a predictable risk: a typo or selecting the wrong person can turn a routine payment into a frustrating problem. I’d verify identifying details with the recipient through a separate conversation if there is any doubt, especially before sending a larger amount. For repeat payments, I would still check the displayed details each time rather than treating a familiar workflow as proof that the destination is correct.
Think carefully at sensitive moments
Shopping is another point where I slow down. Paying through PayPal can mean I do not have to type card details into each participating shop, which is a practical reason to choose it. But I still check the merchant name, total, and delivery details on the checkout screen. The app’s convenience does not tell me whether a seller is trustworthy, whether an item matches its description, or whether a purchase is a good idea.
I would also treat currency and payment choices as decisions to review, not background details. The app can handle different currencies, but that does not mean every conversion or funding choice will be the best one for a particular purchase. When a checkout presents terms or a currency choice, I’d read what is shown and compare it with the option I intended to use. If the cost is unclear, stopping to check is better than assuming the final amount will match the headline price.
What the app can and cannot settle
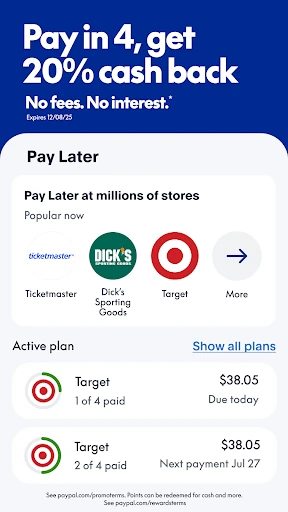
The app’s store summary describes sending and receiving money, shopping, and paying in four. Those uses make it a flexible companion, but they do not make every feature equally relevant to every account or transaction. I would rely on the options presented in my own account and read the terms shown before choosing a payment plan. Splitting a purchase can change how I manage a bill later; it is not a discount or a reason to buy something I would otherwise skip.
For savings, I find the idea of setting money aside appealing as a way to give a goal a visible place in my routine. I would still distinguish that from a full budgeting system: deciding how much I can safely save requires looking at my actual bills and other accounts, not just moving a number inside an app. A simple recurring personal check—what is coming in, what must go out, and what can wait—keeps a savings goal grounded in real life.
Using PayPal with a little more intention
I find that using PayPal more deliberately starts before the payment screen: I decide what the transaction is for and what details I need to verify. That simple habit helps distinguish a casual transfer from a purchase where the seller, total, and displayed terms deserve closer attention. It also makes it easier to choose a bank app, cash, or another route when that fits the situation better.
A realistic everyday workflow
Imagine I meet friends for lunch and one person pays the whole bill. I can send my share once I have confirmed the amount and the recipient’s account details. If I am unsure which contact is correct, I ask rather than guess. Later, when I order something online, I check the seller and total before choosing PayPal at checkout. These are small steps, but they prevent the app’s speed from nudging me into a payment I have not properly reviewed.
For household expenses, I might use the same basic approach to settle a shared purchase: agree on the amount first, then send it with a clear note if the payment screen offers that option. I would not use a casual transfer as a replacement for a proper invoice or a documented business payment when records matter. The right method depends on the relationship and purpose, not only on which button is quickest.
Where it fits among payment alternatives
Compared with a bank’s own app, PayPal can be more convenient when a shop or recipient already uses it, while the bank app may be the more direct choice for checking balances or moving money within my banking relationship. Compared with handing over cash, PayPal is easier when people are apart, but cash can be simpler for a small in-person split and requires no account lookup. A card alone may be quicker at a familiar checkout, while PayPal can be useful when I prefer its available checkout route.
I would not switch between these options based on a blanket claim that one is always safer or cheaper. The practical choice depends on the transaction, the terms visible at the moment, and whether I need a record or a particular payment method. If I am paying a person I do not know, I take extra care to understand what kind of transaction I am making and what protections or terms are displayed. For a purchase from an unfamiliar seller, I would compare the available payment methods rather than assume that using a well-known app guarantees a good outcome.
Agency means checking the details
In my experience, the most useful form of control is an intentional pause before confirming a payment. I check the destination, amount, and any selected source of funds; for a purchase, I check the merchant and total too. I also keep my sign-in details private and avoid making financial decisions while distracted. These habits do not depend on a particular security claim, and they help me stay aware of what I am authorizing.
If something looks wrong, I would use the account’s available help and transaction controls promptly, while keeping any relevant messages or receipts. I would not assume that contacting support can reverse every payment or resolve every disagreement. That is why prevention—careful recipient checks, clear agreements, and a review before confirming—is more useful than relying on a rescue after a mistake.
Who will appreciate it—and who may not
This is a good fit for someone who regularly pays at participating online shops, sends money to people who already use the service, or wants a single app for several everyday payment tasks. It is also approachable for someone who values a familiar flow more than a specialized budgeting dashboard. PayPal is free to download, is rated for Everyone, and the current Android version is 8.98.1, with Android 7.0 or later listed as the minimum requirement.
I would skip it as my main choice if I only need to view bank balances, prefer to keep payment activity within my bank, or rarely encounter merchants and people who accept it. Someone who wants detailed household budgeting should look for a dedicated budgeting approach rather than expect a payment app to explain spending patterns on its own. And anyone uncomfortable managing another financial account may be better served by the payment methods they already understand.
My cautious verdict
Ever had that moment when you're at a café with friends, and it's time to split the bill? That's when PayPal - Pay, Send, Save swoops in like your favorite superhero. This app isn’t just about transferring money; it’s about making life a tad bit easier. I’ve been using it for a while now, and here’s the lowdown.
Easy Peasy Setup
Getting started with PayPal is as simple as pie. You download the app, sign up or log in with your existing account, and you're good to go. It’s like the app just knows you, and before you know it, you’re zooming through payments like a pro. What's cool is that you can link it to your bank account or card, and it handles different currencies effortlessly.
Send and Receive Money
Sending money is as straightforward as texting. Just pop in the recipient's email or phone number, enter the amount, and hit send. The funds land in their account faster than you can say "done." Receiving money? Even easier. You get a notification, and boom, the funds are in your account, ready for whatever adventure you choose next.
Shopping Made Simple
If shopping is your cardio, PayPal’s got you covered. Tons of online stores accept PayPal, so you can shop without ever reaching for your wallet. It’s secure, and you can even score some sweet deals and cashback offers. Trust me, your bank account will thank you.
Security You Can Rely On
In today’s world, security is a big deal. With PayPal, I feel like my money is tucked away in a digital Fort Knox. The app uses encryption and keeps your financial details hidden from prying eyes. Plus, if anything fishy happens, PayPal’s customer service is just a tap away, ready to jump in and save the day.
Saving and Budgeting
One of the features I didn’t expect to love is the ability to save. You can set aside funds for a rainy day or even budget for that dream vacation. It’s like having a mini financial advisor in your pocket, without the hefty price tag.
To wrap it up, PayPal - Pay, Send, Save is more than just an app; it’s a lifeline for managing money in our fast-paced world. Whether you're shopping, sending cash to friends, or stashing away savings, it’s got your back. So, if you haven’t jumped on the PayPal train yet, what are you waiting for? Download it and start simplifying your life today!
4.2
431.72K Reviews
Pros
- Widely accepted for online payments.
- Seamless integration with e-commerce sites.
- Fast and secure money transfers.
- User-friendly interface for quick setup.
- Strong encryption ensures data safety.
Cons
- Transaction fees can be high.
- Limited customer service options.
- Account holds can occur without notice.
- Currency conversion fees apply.
- Limited features in certain regions.


